Definition
Accounting is the process of recording and categorizing financial transactions related to a business. The accounting process includes summarizing, analyzing, and reporting these transactions to oversight agencies, regulators, and tax collection entities. The financial statements used in accounting are a concise summary of financial transactions over an accounting period, summarizing a company’s operations, financial position, and cash flows.
Accounting Process
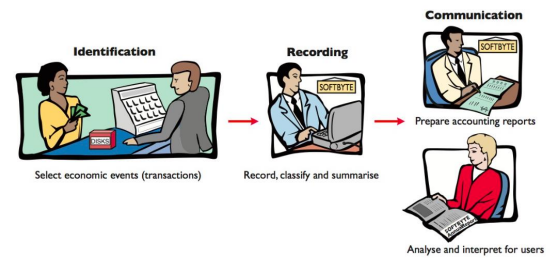
Accounting involves identifying, measuring, recording, and communicating information to users to help them make decisions.
- Identifying transactions and events that relate to an entity
- Measuring (quantifying) them in monetary terms
- Recording them in the accounting system
- Communicating the information in a meaningful format to users
Role of Accounting
Accounting’s key function is to provide information for decision making. It is used by businesses large and small, by for-profit, not-for-profit and government entities, and by individuals.
Key Accounting Elements
These five elements are the foundation of financial reporting. Their definition criteria are set out in the Conceptual Framework.
Each element has specific items, and an account (record) is kept for each item the business transacts in.
Applying the Definitions
To decide whether an item should be recorded:
- Decide which element is appropriate.
- Analyse the definition criteria step by step, and conclude whether the item meets the definition.
- Analyse the recognition criteria step by step, and conclude whether the item meets them.
- Conclude whether the item should be recorded in the business records.
Accounting Equation
The basic equation uses the three Balance Sheet elements:
Income increases equity and expenses decrease it, so profit or loss (Income − Expense) is added to (subtracted from) opening equity. This gives the expanded equation:
The equation must ALWAYS balance. In the accounting system this is done with the double-entry rule: total debits = total credits. See Debit and Credit.
Recording Transactions
Transactions are recorded in the steps of the accounting cycle:
- Analyse the transaction
- Record it in the General Journal
- Post it to the General Ledger, then balance the ledger accounts